 John Veale Solicitor
How to Avoid Probate on Bank Accounts? Probate is the process that determines heirs, pays creditors and distributes assets after a person dies.
The whole thing is expensive and slow. And on top of the cost and the waiting it can leave the people you care about dealing with grief and anxiety at the same time they’re dealing with paperwork and court dates and legal fees they didn’t expect.
But you can avoid probate on bank accounts if you plan ahead. Takes some setup and probably a conversation with an attorney or financial advisor who knows your situation, but the tools exist and most of them are free or close to it. The point is to make sure your money goes where you want it to go without a judge having to sign off on it first.
Simple Ways To Avoid Probate on Bank Accounts
Payable-on-death (POD) accounts
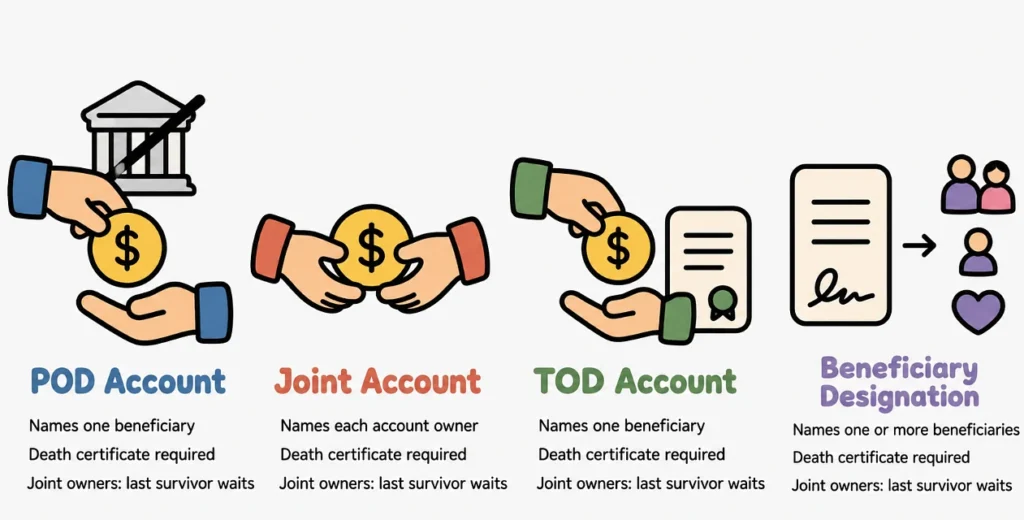
So a POD account is probably the simplest way to keep your bank money out of probate and most people don’t even know it exists. You go to your bank, fill out a form, name someone as the beneficiary, and that’s it. When you die the money goes directly to that person, no court, no waiting, no legal fees.
Works on checking accounts, savings accounts, certificates of deposit (CDs), money market accounts, basically anything your bank holds for you. And it costs nothing to set up which is the part that surprises people because they assume anything that avoids probate must involve lawyers and trust documents and thousands of dollars in fees. It doesn’t.
Your beneficiary just needs to bring a certified copy of the death certificate and some proof of who they are. Bank verifies it, releases the funds, done.
One thing to know though. If the POD account was jointly owned by more than one person then the beneficiary typically has to wait until all owners have died before they can actually claim the money. Catches some families off guard when they find that out.
So does a POD account replace having an estate plan? No, and this is where people get tripped up. A POD handles that one specific account and nothing else. It doesn’t cover your house or your car or your retirement accounts or anything outside that bank.
If you name one child as the POD beneficiary on your savings account but your will says everything splits equally between three kids, you’ve just created exactly the kind of family argument you were trying to avoid. The POD designation overrides the will. Every time. So it needs to fit inside a bigger plan, not be the whole plan by itself.
Joint accounts
Joint bank accounts work differently and they’re worth understanding separately because people use them for all kinds of reasons that have nothing to do with probate and then find out later that probate was affected anyway.
A joint account is just a bank account where two people share ownership. Both can deposit and withdraw, both can write checks, both have full access. When one owner dies the surviving owner keeps the account automatically through what’s called right of survivorship, and because the surviving owner already legally owns the account there’s nothing for probate to process.
Money stays accessible immediately. That part works well.
Couples use these all the time for shared expenses, saving for a house, paying bills together. Makes sense for that purpose. But it’s important to consider whether adding someone to your account just to avoid probate is actually a good idea.
Why not? Because joint ownership means joint access and joint liability while you’re still alive. You add your adult child to your bank account and now their creditors can potentially come after those funds if they get sued or go through a bankruptcy. That’s your money at risk because of someone else’s financial problems.
There’s also the relationship side of it. Different spending habits, different priorities, different comfort levels with money. All of that comes into play when you open a joint account and it’s worth having an honest conversation about expectations before you do it rather than after something goes wrong.
Transfer-on-death (TOD) accounts
TOD accounts do roughly the same thing as POD accounts but for non-retirement investment accounts. Your brokerage account, your stock portfolio, mutual funds, that sort of thing. You name a beneficiary on the account and when you die the assets transfer directly to that person without going through probate.
The mechanics are basically identical to how beneficiary designations work on retirement accounts like IRAs and 401(k)s. You fill out the paperwork with your brokerage, name who you want to receive the assets, and the firm handles the transfer when the time comes. Court doesn’t get involved at all.
Should you set one up? If you have investment accounts outside of retirement plans then yes, almost certainly. Without a TOD designation those accounts go through probate by default and probate on investment accounts can get complicated fast, especially if the market is moving and nobody has authority to make decisions about the holdings while the court process drags on.
One thing to stay on top of though. Review your TOD designations periodically and make sure the people you’ve named are still the people you want receiving those assets.
Life changes. Relationships change. Someone you named five years ago might not be the right choice today and if you don’t update the form the old designation stands regardless of what your will says. Same override rule as POD accounts. The designation on file with the institution wins.
Also worth knowing that TOD and POD accounts aren’t shielded from creditor claims against your estate. The money transfers outside of probate but if your estate owes debts those creditors can still potentially come after the funds. Not a reason to avoid setting them up, just something to be aware of so you’re not assuming the money is completely untouchable once a beneficiary is named.
Beneficiary designations
This is really the umbrella that covers everything above and it’s the single most important thing you can do to keep your assets out of probate without spending a lot of money or setting up complicated legal structures.
Any account that has a valid beneficiary designation – life insurance, retirement accounts, POD accounts, TOD accounts – passes directly to the named person when you die. Doesn’t go through court. Doesn’t wait for a judge. The institution that holds the account handles the transfer and your beneficiary gets access to the funds typically within a few weeks.
What’s the catch? People set these designations and then forget about them for years.
You named your spouse as primary beneficiary on your 401(k) when you were twenty-eight and now you’re fifty-two and divorced and remarried but the form still says your ex-spouse’s name. That designation controls where the money goes. Not your current will, not your new marriage, not your intentions. The form on file.
So check them. All of them. Your life insurance, your retirement accounts, your bank accounts, your investment accounts. Make sure the names match what you actually want and make sure they’re consistent with the rest of your estate plan.
Takes maybe an afternoon to pull everything together and review it. That afternoon could save your family months of legal fighting and thousands in attorney fees.
You can name more than just your spouse too. Children, friends, charities, basically anyone you want. And you can name contingent beneficiaries who receive the assets if your primary beneficiary dies before you do. Most people don’t bother with contingent beneficiaries and honestly it’s one of those things that feels unnecessary until it matters, and then it matters a lot.